Filtered Press Release : 2026 Nov
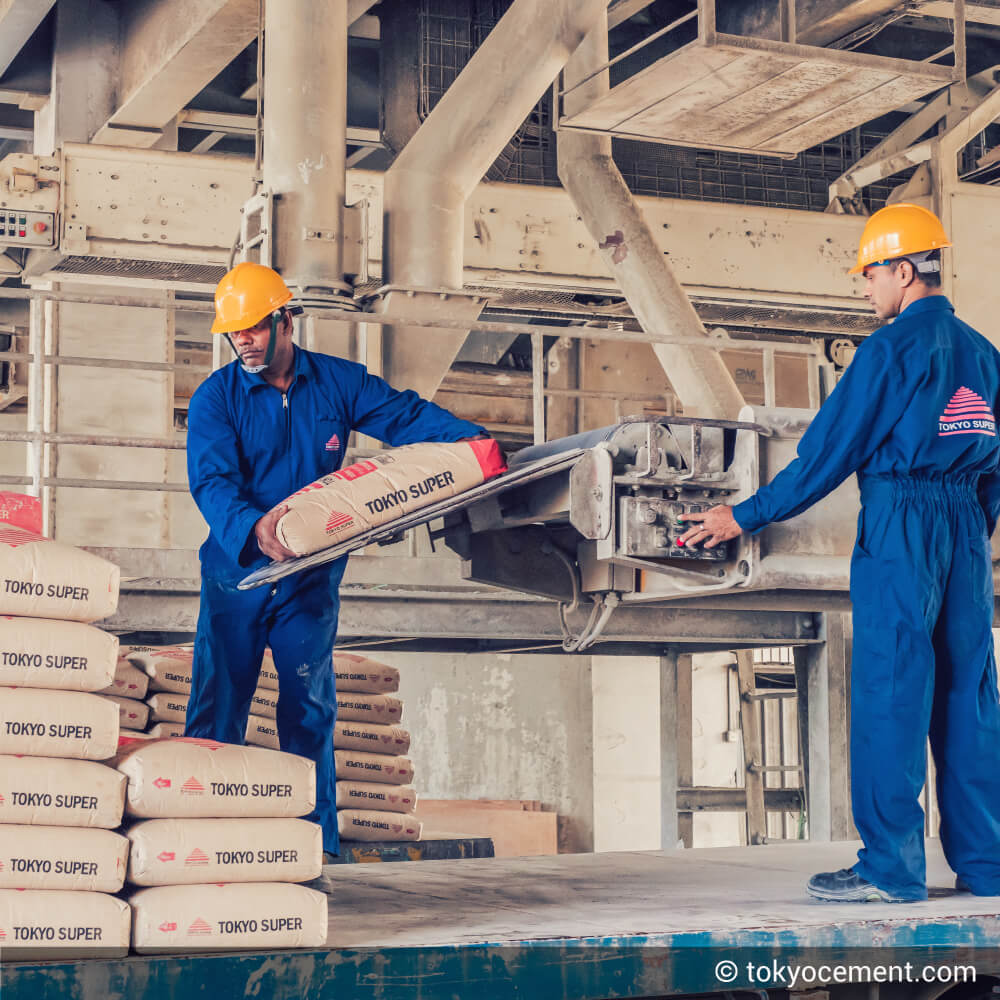
Tokyo Cement Group Strengthens Market Position to Sustain Growth in FY2627 Q2
Quarterly Financial Review Tokyo Cement Group (Tokyo Cement) reported a turnover of Rs. 20,944 million for the 2nd quarter ending 30th September 2026, reflecting a 28% increase from Rs. 16,322 million recorded in the corresponding period of the previous year. Profit After Tax (PAT) stood at Rs. 870 million, compared to Rs. 1,003 million in …
Quarterly Financial Review
Tokyo Cement Group (Tokyo Cement) reported a turnover of Rs. 20,944 million for the 2nd quarter ending 30th September 2026, reflecting a 28% increase from Rs. 16,322 million recorded in the corresponding period of the previous year. Profit After Tax (PAT) stood at Rs. 870 million, compared to Rs. 1,003 million in the same period last year.
The increase in turnover reflects the growth in volume and price increase from the previous quarter. However, profitability remained under pressure due to elevated raw material costs and currency volatility during the period.
The Economic Environment
The volatile and unpredictable nature of the Iran conflict continued to cloud the economic outlook during the quarter, with frequent fluctuations in global fuel prices and the looming threat of complete disruption of diesel supply weighing heavy on consumer confidence. These uncertainties, compounded by rising energy costs and climate-related risks, contributed to a more cautious investment climate and moderated economic momentum during the quarter.
The domestic economy faced mounting cost pressures, with fuel and energy expenditure rising sharply alongside a global fertilizer shortage, and the potential impact of severe El Niño conditions on the agriculture sector. Over the quarter, the Rupee was observed to depreciate against the US Dollar increasing pressures on reserves. Furthermore, year-on-year headline inflation, measured by the National Consumer Price Index (NCPI) reached 8.1% in August, exceeding the Central Bank’s target range for a second consecutive month.
Despite these headwinds, several indicators pointed to continued resilience in the external sector. Gross official reserves increased, supported by improved revenue collection and prudent government expenditure, while export earnings and worker remittances sustained foreign exchange inflows despite subdued global demand and rising shipping costs. Tourism earnings also showed signs of recovery ahead of the peak season. Against this backdrop of heightened global and climate-related uncertainty, the Central Bank decided to maintain the Overnight Policy Rate (OPR) at 8.75% throughout the July to September quarter.
Further reinforcing investor confidence, Fitch Ratings upgraded Sri Lanka’s credit rating to ‘B-’ with a Stable Outlook, citing stronger-than-expected fiscal and external sector performance. This marked a notable improvement from the ‘CCC+’ rating assigned since November 2020, signaling progress in the country’s economic recovery.
Against this mixed macroeconomic backdrop, Sri Lanka’s cement industry moved to strengthen market resilience by maintaining uninterrupted supply and stable market prices despite significant increases in raw material, freight, insurance and fuel costs. Cement consumption continued its upward trajectory during the quarter, supported by favourable weather conditions and the availability of construction materials. The Sri Lanka Purchasing Managers’ Index for Construction (PMI-Construction) also indicated continued industry expansion with new orders stemming from state-led development projects, although supply chain disruptions in the Middle East constrained the availability of bitumen, required for road construction activities.
Tokyo Cement Group further strengthened its market position during the quarter, gaining market share as coastal shipping improved access to the Western Province and beyond. The expanded market reach supported higher utilisation of the Group’s enhanced production capacity, driving greater operational efficiency.
However, as a result of currency depreciation and global cost increases, all material inputs, both locally manufactured and imported, increased in price, thereby softening investment sentiment among private developers and individual investors. These pressures also threatened to further impede the implementation of public sector development projects.
Outlook
As the financial sector anticipates a moderation in private sector credit growth over the coming quarters, the trajectory of the Middle East conflict, global energy prices and supply chain conditions will remain critical determinants of national economic momentum and sectoral growth prospects.
Against this backdrop, the sovereign credit rating upgrade represents a significant positive development, with the potential to strengthen investor confidence and attract diversified foreign currency inflows. Despite persistent external shocks, the national economic outlook remains broadly stable, underpinned by sustained fiscal revenue and steady forex remittances. However, elevated import costs and a slower-than-anticipated recovery in tourism continue to pose near-term challenges, while geopolitical tensions and weather-related uncertainties remain key downside risks.
Realising the economy’s growth potential will depend on timely execution of public sector infrastructure projects and the policy direction set out in the forthcoming November budget. Together, these will be instrumental in translating improving macroeconomic confidence into tangible economic activity and investment.
Within this broader context, the construction sector maintains a cautiously optimistic outlook, supported by infrastructure development initiatives already underway by regional government institutes. Sustaining this momentum will depend on the timely commencement and implementation of planned large-scale public investment projects, alongside an enabling policy environment that encourages private sector participation and reinforces investor confidence.
Tokyo Cement maintains a conservative short- to medium-term outlook, while remaining confident in the country’s economic fundamentals. With an enhanced production capacity the Group is well positioned to capitalise on future industry growth. Tokyo Cement will continue to exercise strict cost discipline, safeguard stakeholder interests, and play an active role in supporting the country’s construction-led economic recovery. —
காப்பகம்
| 2026 | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |
| 2025 | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |
| 2024 | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |
| 2023 | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |
| 2022 | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |
| 2021 | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |
| 2020 | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |
| 2019 | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |
| 2018 | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |
| 2017 | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |